Many Americans are unaware of the economic disparities that leave some Israelis struggling to obtain loans, according to Eldan Kaye, vice president of development and partnerships at the Israeli nonprofit lender Ogen.
“People hear Israel and they hear ‘startup nation’ in terms of its economy, and often people aren’t aware of the disparities within the economy here and the challenges with the banking sectors,” he told JNS.
Ogen, which says that it has provided more than 86,000 loans totaling $990 million over more than three decades, aims to establish what its executives say would be Israel’s first nonprofit bank.
The organization is seeking $150 million in philanthropic support, including from American Jews, to “bring the bank to a situation where it almost stands on its own two feet and continues growing based on that initial injection of philanthropy,” according to Kaye.
The nonprofit also aims to increase its 17,000 to 20,000 customers to 150,000 served over the next eight years.
Kaye and Sagi Balasha, Ogen’s CEO, talked to JNS ahead of a trip to the United States, where they hope to introduce Americans to Israel’s economic disparities.
They also plan to meet with prospective donors and to attend the annual meeting of the American Friends of Ogen board, which has “four new potential additions to the board,” Kaye said.
“A lot of it is around friend-raising as opposed to fundraising,” he told JNS.
Balasha, who joined the video interview from Ben Gurion Airport before his flight, told JNS that the nonprofit applied to the Bank of Israel for a banking license in August and submitted a business plan about 300 pages long.
Regulators are reviewing it, he said.
The nonprofit hopes to open the bank on Jan. 1, 2028, if approvals come through.
The proposal follows a sharp increase in demand for Ogen’s services during the war. Its loan distribution has roughly tripled since Oct. 7, according to Kaye.
“That’s definitely due to the demand, but it’s also due to the fact that philanthropy and impact investors have seen us as a vehicle to really meet people at their needs on the ground very, very quickly,” he told JNS.
Unlike commercial banks, the proposed institution would have “no shareholders that receive dividends,” Kaye said. Rather than a “metric of profit,” its success would be measured by a “metric of impact,” he said.
“That enables us to utilize capital in a way that looks at people’s needs and their potential, as opposed to what traditionally may have been deemed risky and unprofitable,” he told JNS.
Ogen’s current loan portfolio stands at about $323 million, which Balasha hopes to increase to $1.6 billion within eight years if it obtains a banking license.
A license would also allow Ogen to accept deposits and offer checking accounts, services it cannot currently provide. The nonprofit is also trying to acquire Ofek, an Israeli credit-union initiative that developed banking infrastructure but has yet to begin operations.
Balasha said that the proposed bank would combine Ofek’s technology with Ogen’s lending experience and capital.
American Jews and other customers abroad could also open accounts, earning interest on their deposits while helping finance loans to underserved borrowers, he said.
“You can do good and do well at the same time,” Balasha told JNS.
Elise Brezis, professor of economics at Bar-Ilan University and director of its center for banking in the economics department, is a former head of the statistics division and research department at the Bank of Israel and was president of the Israeli Association for the Study of European Integration.
Brezis, who isn’t involved with Ogen, questioned if it needs a banking license to expand its work.
“I think that they do a great job,” she told JNS. “But the idea that they will become a nonprofit bank, I’m not sure that I would like this definition.”
The transition to becoming a bank could introduce regulatory complications and “can give place to corruption,” she cautioned.
Brezis also questioned if microfinance, offering financial services to low-income individuals or businesses, should operate within the traditional banking system.
“The financial system is very sophisticated,” she told JNS. “To try to mix things together is like you want a company selling orange juice to be part of a company selling shoes.”
Ogen is doing “extremely important” work for poor Israelis and small businesses, Brezis said. “Ogen helps people learn how to fish—not just to eat the fish. This is very important for the Israeli economy.”
When JNS told Brezis that Ogen was seeking a banking license to be able to accept deposits and offer checking accounts, she said that was something about which she needed to think more.
“I’m not sure I want one more bank that the regulation should be different,” she said. “We have to think about it.”
Founded in 1990 as the Israel Free Loan Association, Ogen lends to individuals, small businesses and nonprofits that may have difficulty obtaining credit from traditional banks.
Its approach draws on the Hebrew Free Loan model, which has existed in North American Jewish communities for more than a century, according to Kaye.
“There’s robust systems around the world, but I think in Ogen’s case, or in Israel’s case, Ogen is by far the largest of its kind here, and certainly the banking license would make it a one and only here in Israel,” he said.
The model uses philanthropic donations to provide interest-free loans to families and small businesses, or “tiny businesses,” as Kaye put it.
“The money comes back, and it goes out again over and over and over,” he told JNS.
Israel’s banking system leaves many low-income households and small businesses with limited access to credit, according to Balasha.
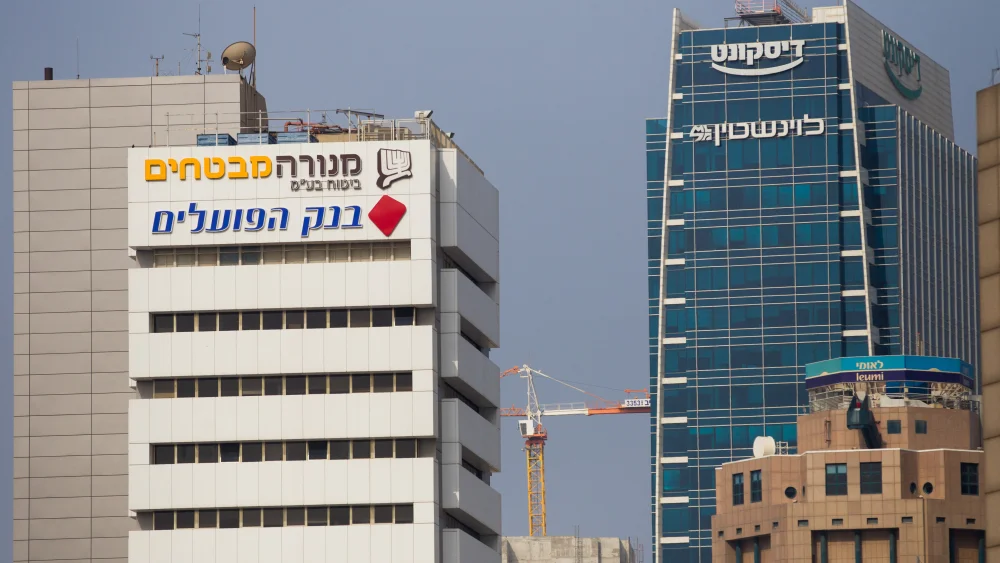
The country’s five largest banking groups—Hapoalim, Leumi, Discount, Mizrahi-Tefahot and First International—controlled about 98% of the sector’s assets at the end of 2024, according to Israel’s Competition Authority.
In May, the authority designated the five as a “concentration group,” or a small number of companies operating in a market with limited competition.
Balasha contrasted Israel with the United States, where thousands of banks, credit unions and community lenders offer borrowers more options, he said.
Israeli banks “all prefer high-income population,” he told JNS. “They all prefer big businesses.”
“The market doesn’t provide the needed solution for those populations, as those populations, in a way, they don’t have access to credit,” he said. “When you don’t have access to credit, your ability to build your life is very limited.”
Kaye described Ogen as a “social lender” that practices “values-based banking,” an approach that allows it to finance businesses traditional lenders may consider too risky.
Israeli banks generally refuse to finance restaurants, for example, but Ogen “has the ability to look at the entrepreneur in the eyes, understand their background, understand the potential, look at the business plan, help them sometimes create the business plan and then ultimately give them the capital needed to start up this restaurant or to expand it,” Kaye said. (JNS sought comment from Israeli banks.)
“You’ve got this whole ecosystem of economic opportunity that is created on the basis of that sort of one restaurant,” Kaye told JNS.
Philanthropy is already central to Ogen’s lending operation, though not simply because donors provide money for loans.
The nonprofit combines donations with commercial-bank credit lines, government funding and bonds issued to institutional investors, an approach Balasha called “blended finance.”
Unlike money borrowed from commercial lenders, donations do not carry interest payments. They also help protect Ogen against losses when borrowers fail to repay their loans, the nonprofit said.
“When a donor gives us money, we don’t have to pay him any interest,” Balasha told JNS. “So this is an inexpensive source of money that enables us to lend to our borrowers cheaper than the market.”
When Ogen borrows money from a commercial bank, it can set aside philanthropic funds equal to 10% of the amount borrowed to protect against potential losses, according to Kaye.
“If any of these loans don’t come back, you’ve got this cushion that will absorb that missed payment,” he told JNS.
That protection can allow Ogen to borrow 10 to 12 times the amount donated, Kaye said. The nonprofit also uses donations to absorb an initial portion of potential losses on bonds issued to insurance companies and pension funds.
For donors, Balasha said, the advantage is that their contributions can finance far more lending than the original amount.
“On each dollar they’ll donate, we can leverage a few times by raising other sources of capital that are not philanthropic,” he told JNS.
Reservists make up a large percentage of the many “subpopulations” that Ogen serves, Balasha said. He used the example of Omri Ghanim, 33, who was riding in the back of an Israeli military truck in 2024 while his Tel Aviv furniture design business was close to collapse. Minutes before entering Lebanon, Ghanim called Ogen.
The Druze reservist, who commanded about 100 soldiers, had already spent months away fighting after Oct. 7. His clients disappeared, his business was “at a stop” and his “cash flow was very, very low,” he told JNS.
Ghanim, originally from Sajur in northern Israel, gave a representative from Ogen his mother’s phone number and asked him to do what he could. When he returned to Israel several weeks later, he opened his banking mobile app and found that he had received a loan of about $51,500.
The loan “helped me to cross the hardest year I feel I ever had in my five years in the business,” Ghanim told JNS. “Today, my revenue is like twice my revenue in comparison to 2024.”
Ghanim’s business is at a “different point” today than it was when he made the phone call on his way into Lebanon.
The loan “saved me like a Superman and took me from the lowest point I have ever been to a very high point today,” he said. “I have a lot of thanks to Ogen. That’s what they did for me.”